Kidashi
Credit built on a woman's trade, not her collateral.
A livelihood-embedded micro-loan for excluded women traders in Northern Nigeria, delivered on the licensed rails of Payrep Microfinance Bank.
Excluded women traders are financed by moneylenders, not banks.
A trader in a northern market rarely fails because of skill. She fails because working capital arrives late and costs too much.
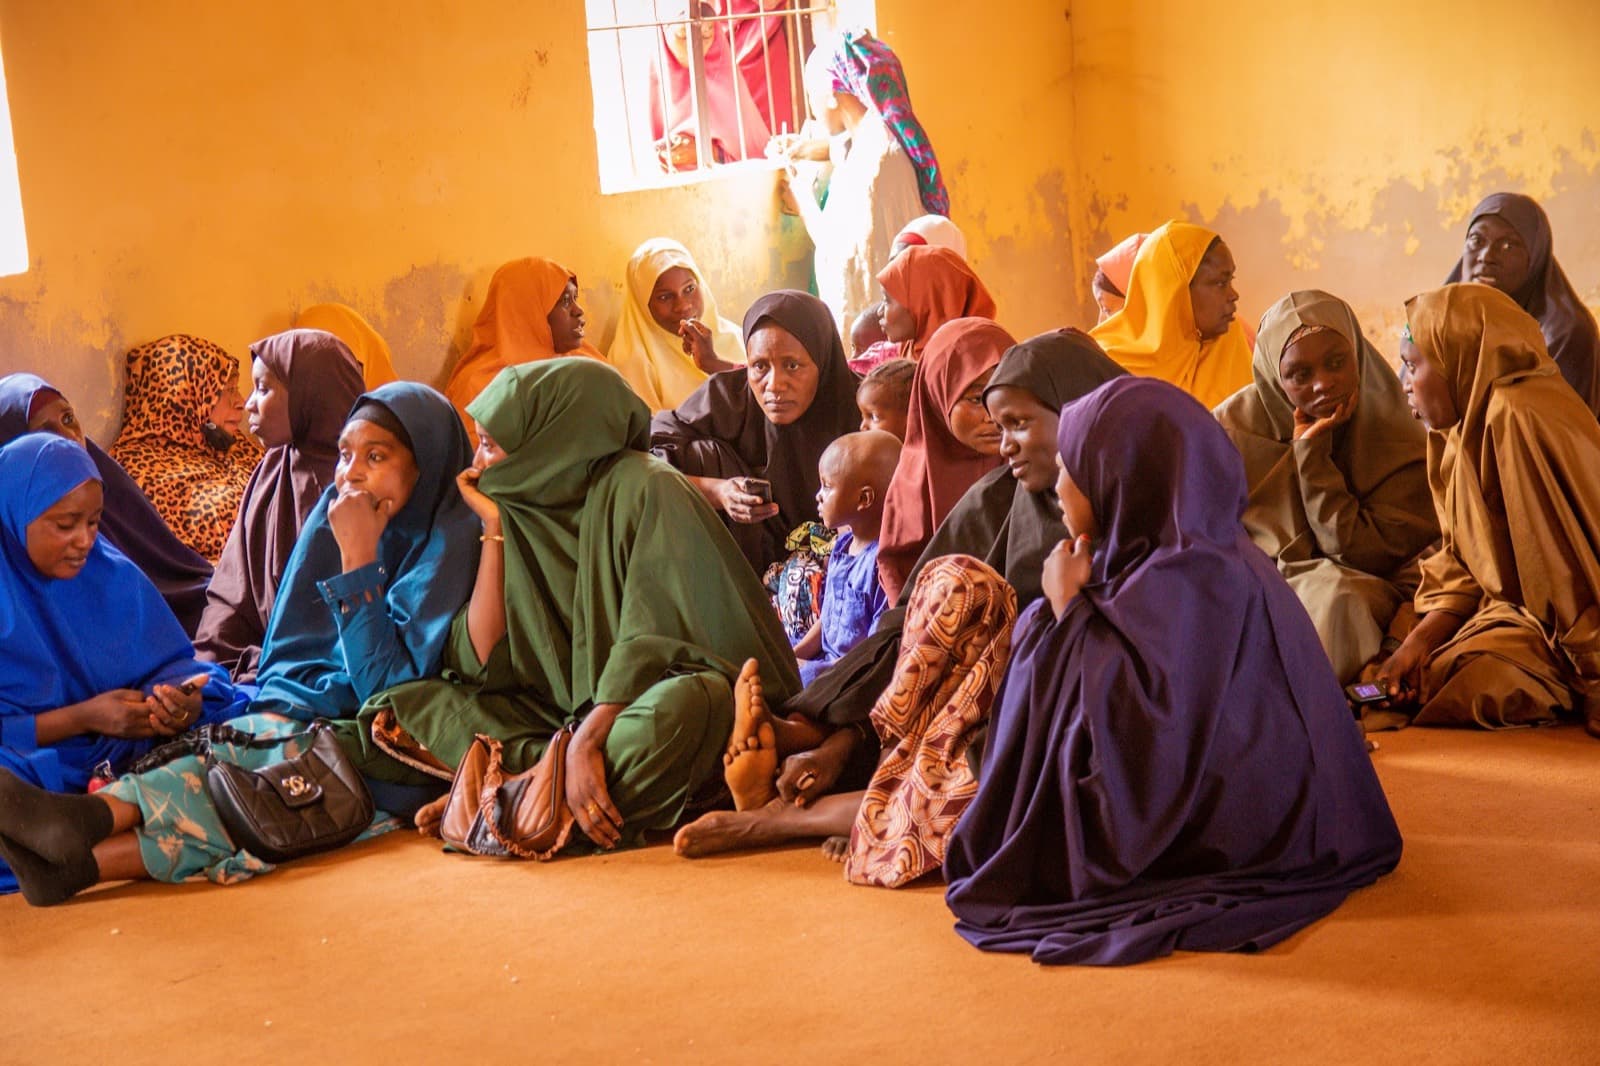
No formal identity trail
Many women trade without a verified national identity, a bank verification number or an account, so no lender can underwrite them.
No collateral, no statements
Bank credit assumes land, payslips or months of statements. Informal traders have none of them.
Punitive informal credit
Daily-collection moneylenders and 'ajo' arrangements price capital far above what a small trading margin can carry.
Cash-only, low digital confidence
First-time users fear PINs, agents and phones. Literacy, not just access, is the real barrier.
A livelihood-embedded micro-loan on a licensed rail.
Kidashi turns a woman's trading activity, not her collateral, into her credit record. A trusted community circle vouches for her, a field agent onboards her with a verified identity, and Payrep MFB disburses into a wallet she can use at the market the same day.
Identity first
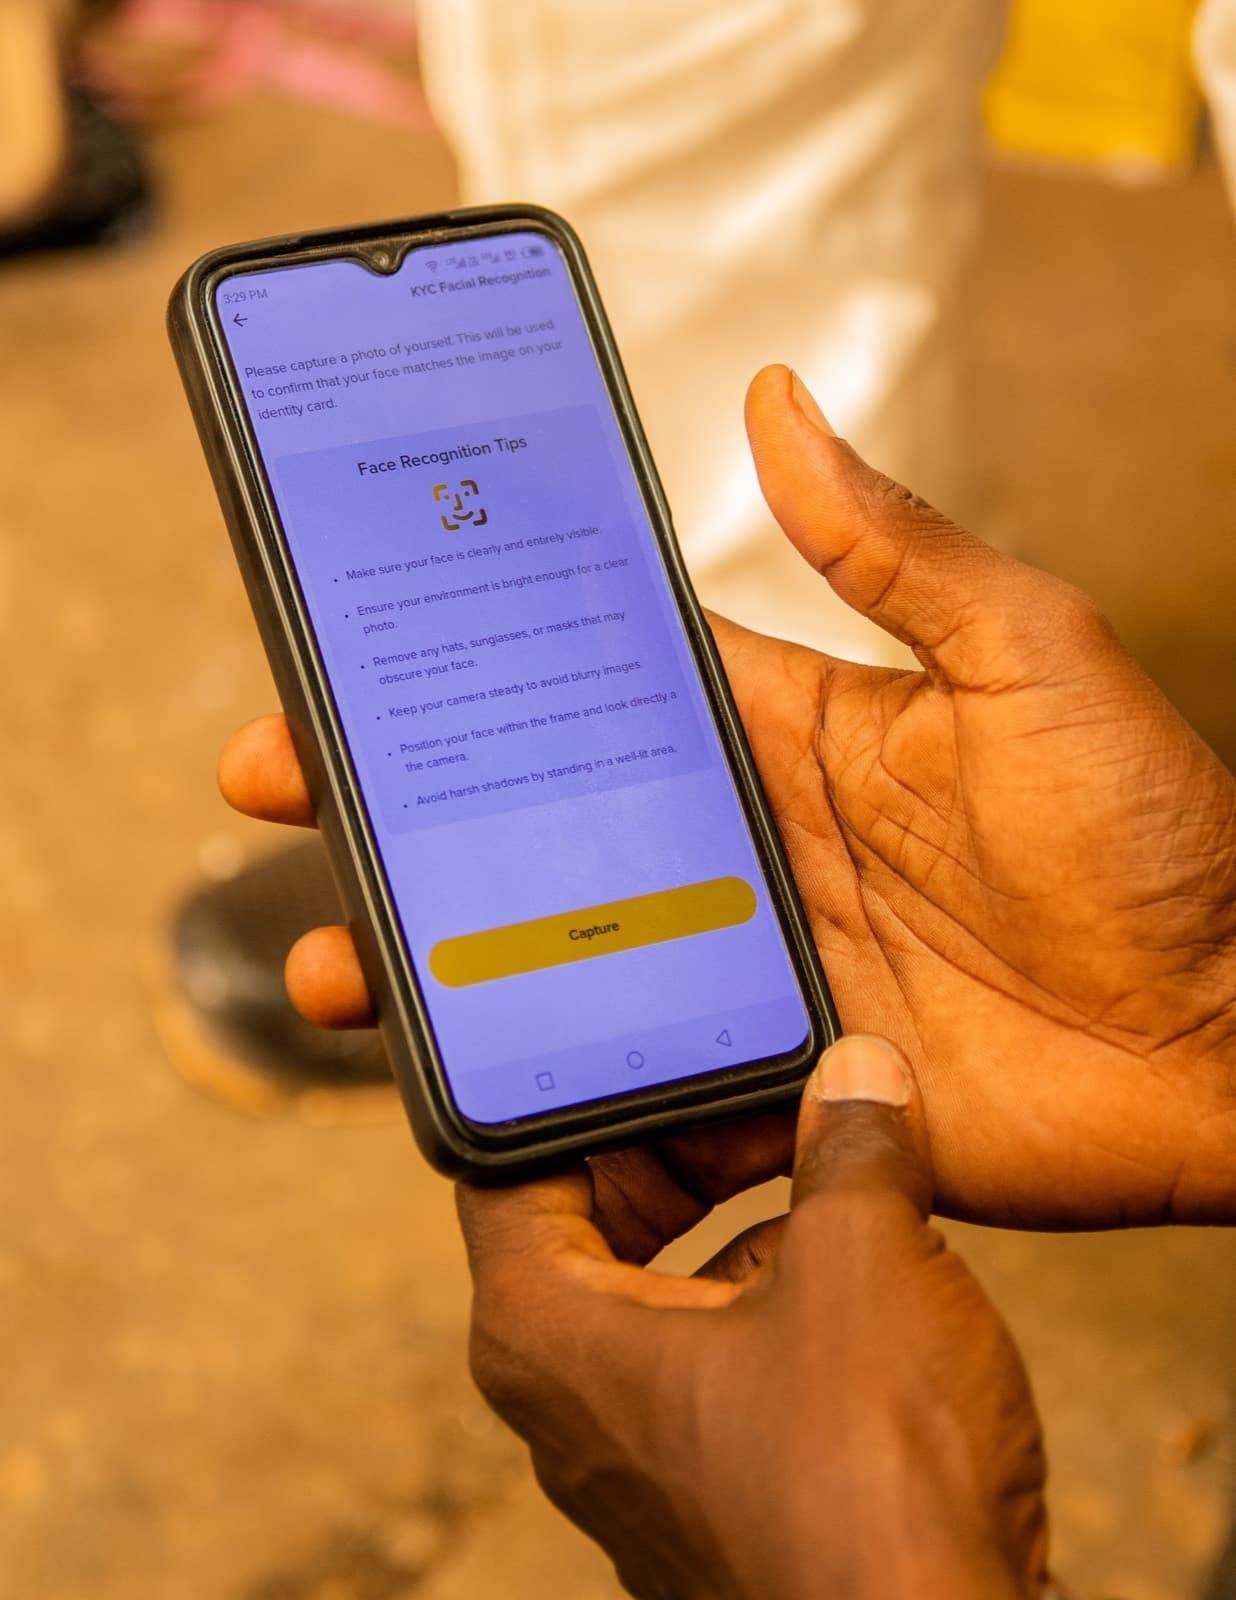
National identity capture and verification at the point of onboarding creates a permanent, portable financial identity.
Circle guarantee
Small circles of women co-guarantee each other. Social capital replaces the collateral she does not have.
Small, fast, cyclical
Loans start small and grow with repayment behaviour, matched to short trading cycles.
Agent-delivered
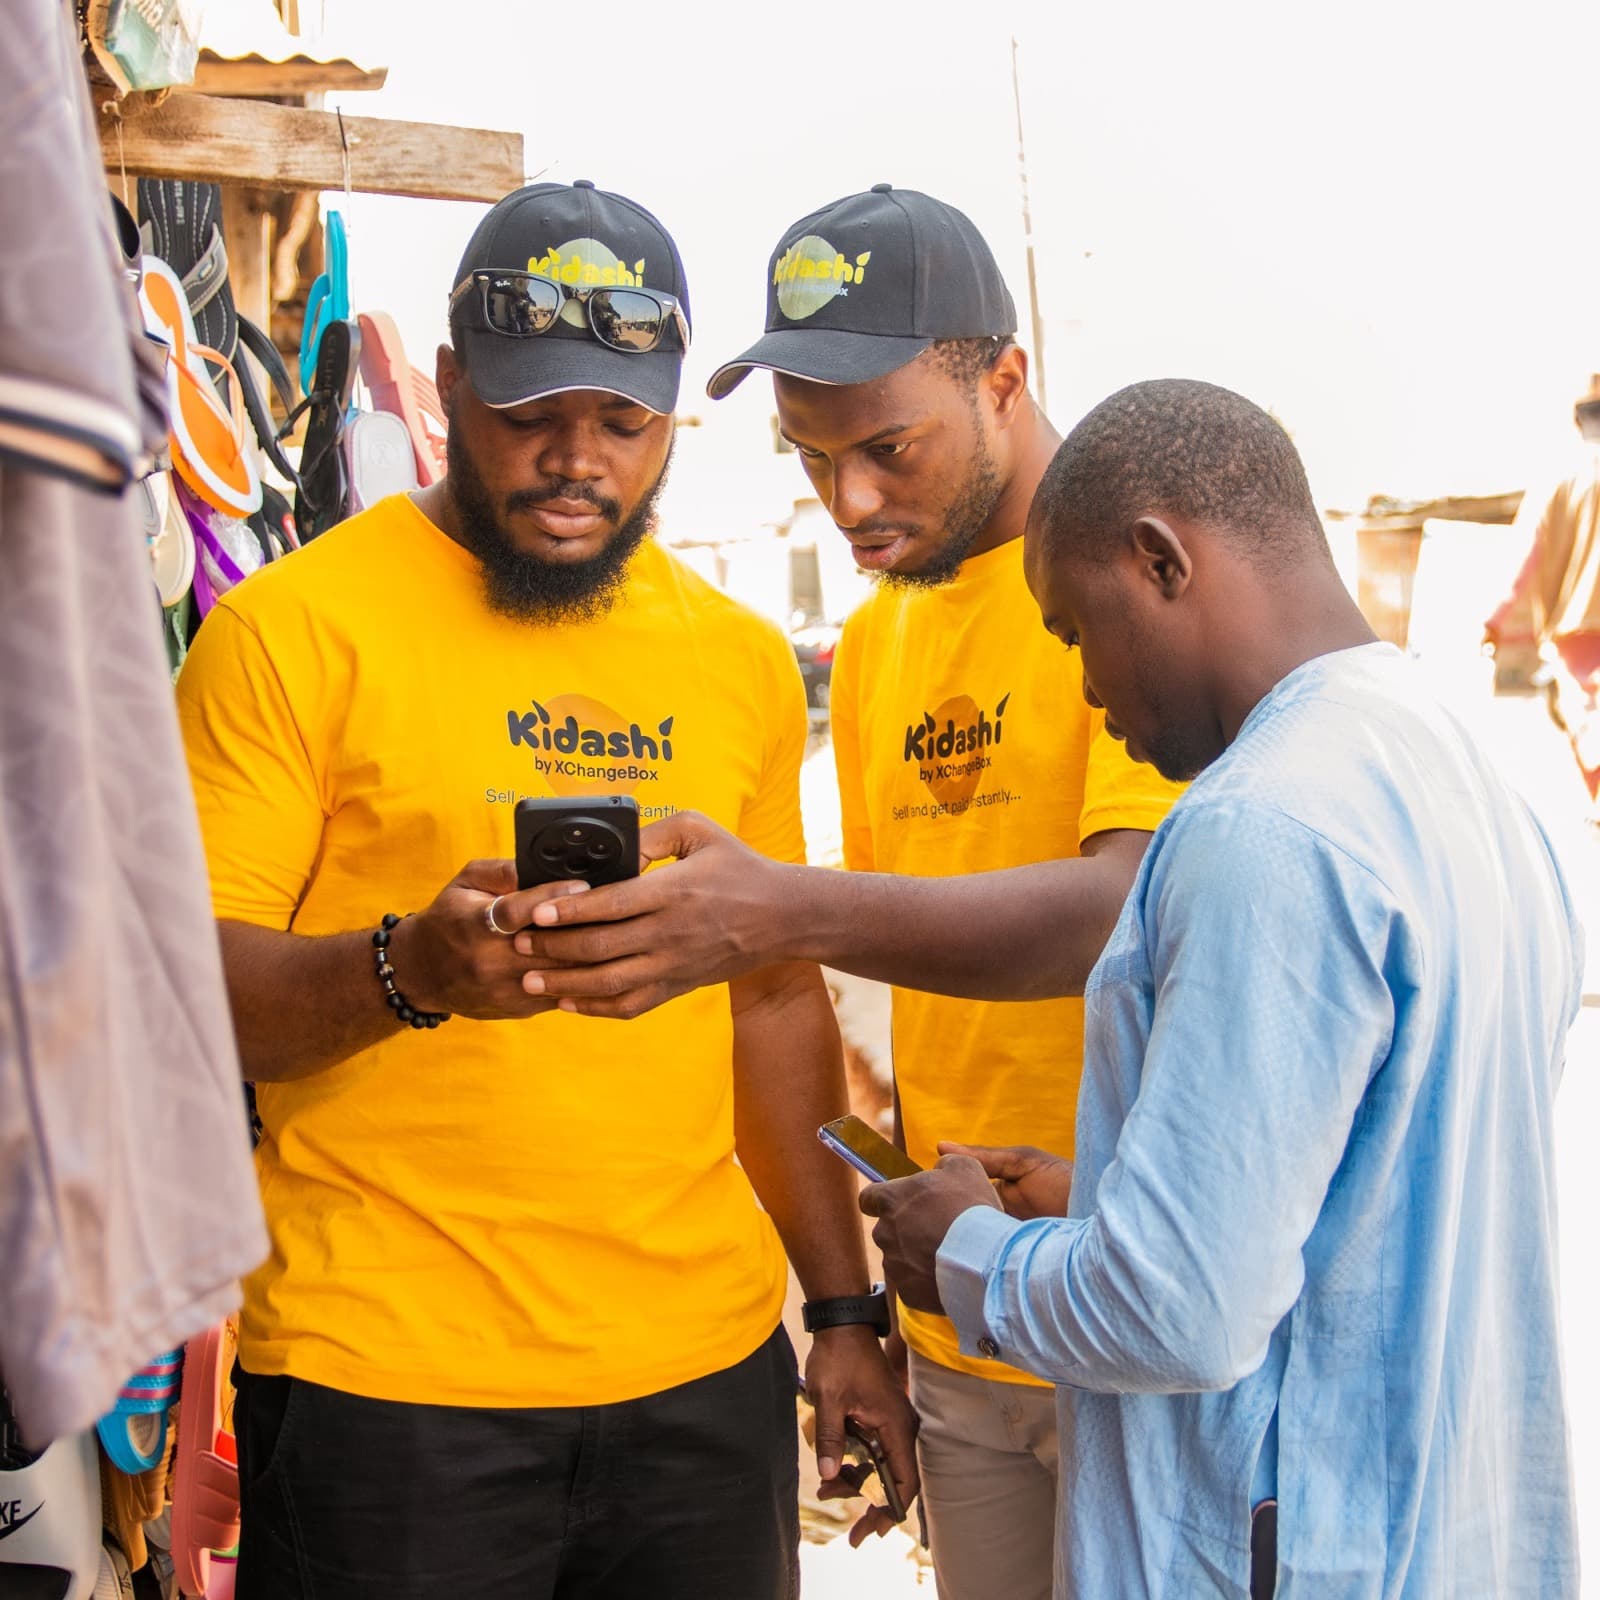
A local agent within reach handles onboarding, training, disbursement support and collections.
Every element sits on Payrep Microfinance Bank, a CBN-licensed institution, so deposits, lending and settlement are fully regulated.
From first contact to repeat cycle.
Each cycle is matched to her trading rhythm, then repeats and grows.
- 01
Community entry
Traditional and market leaders introduce the agent, and women self-select into small circles.
- 02
Identity onboarding
The agent captures and verifies her national identity and opens a Payrep wallet on the spot.
- 03
Literacy session
A vernacular session on accounts, PIN safety, fraud and repayment, before any money moves.
- 04
Assessment
Stock turnover, market presence and circle endorsement size the first ticket, deliberately small.
- 05
Disbursement
Funds land in her wallet, and she buys stock from trained vendors who accept digital payment.
- 06
Repayment
Micro-instalments over the trading cycle via USSD, agent POS or wallet sweep.
- 07
Graduation
A clean cycle unlocks a larger ticket, a longer tenor and wider XchangeBox trade finance.
Built for the women banks overlook.
Rural and peri-urban, paid in daily or weekly cash, often on a basic phone and new to formal finance.
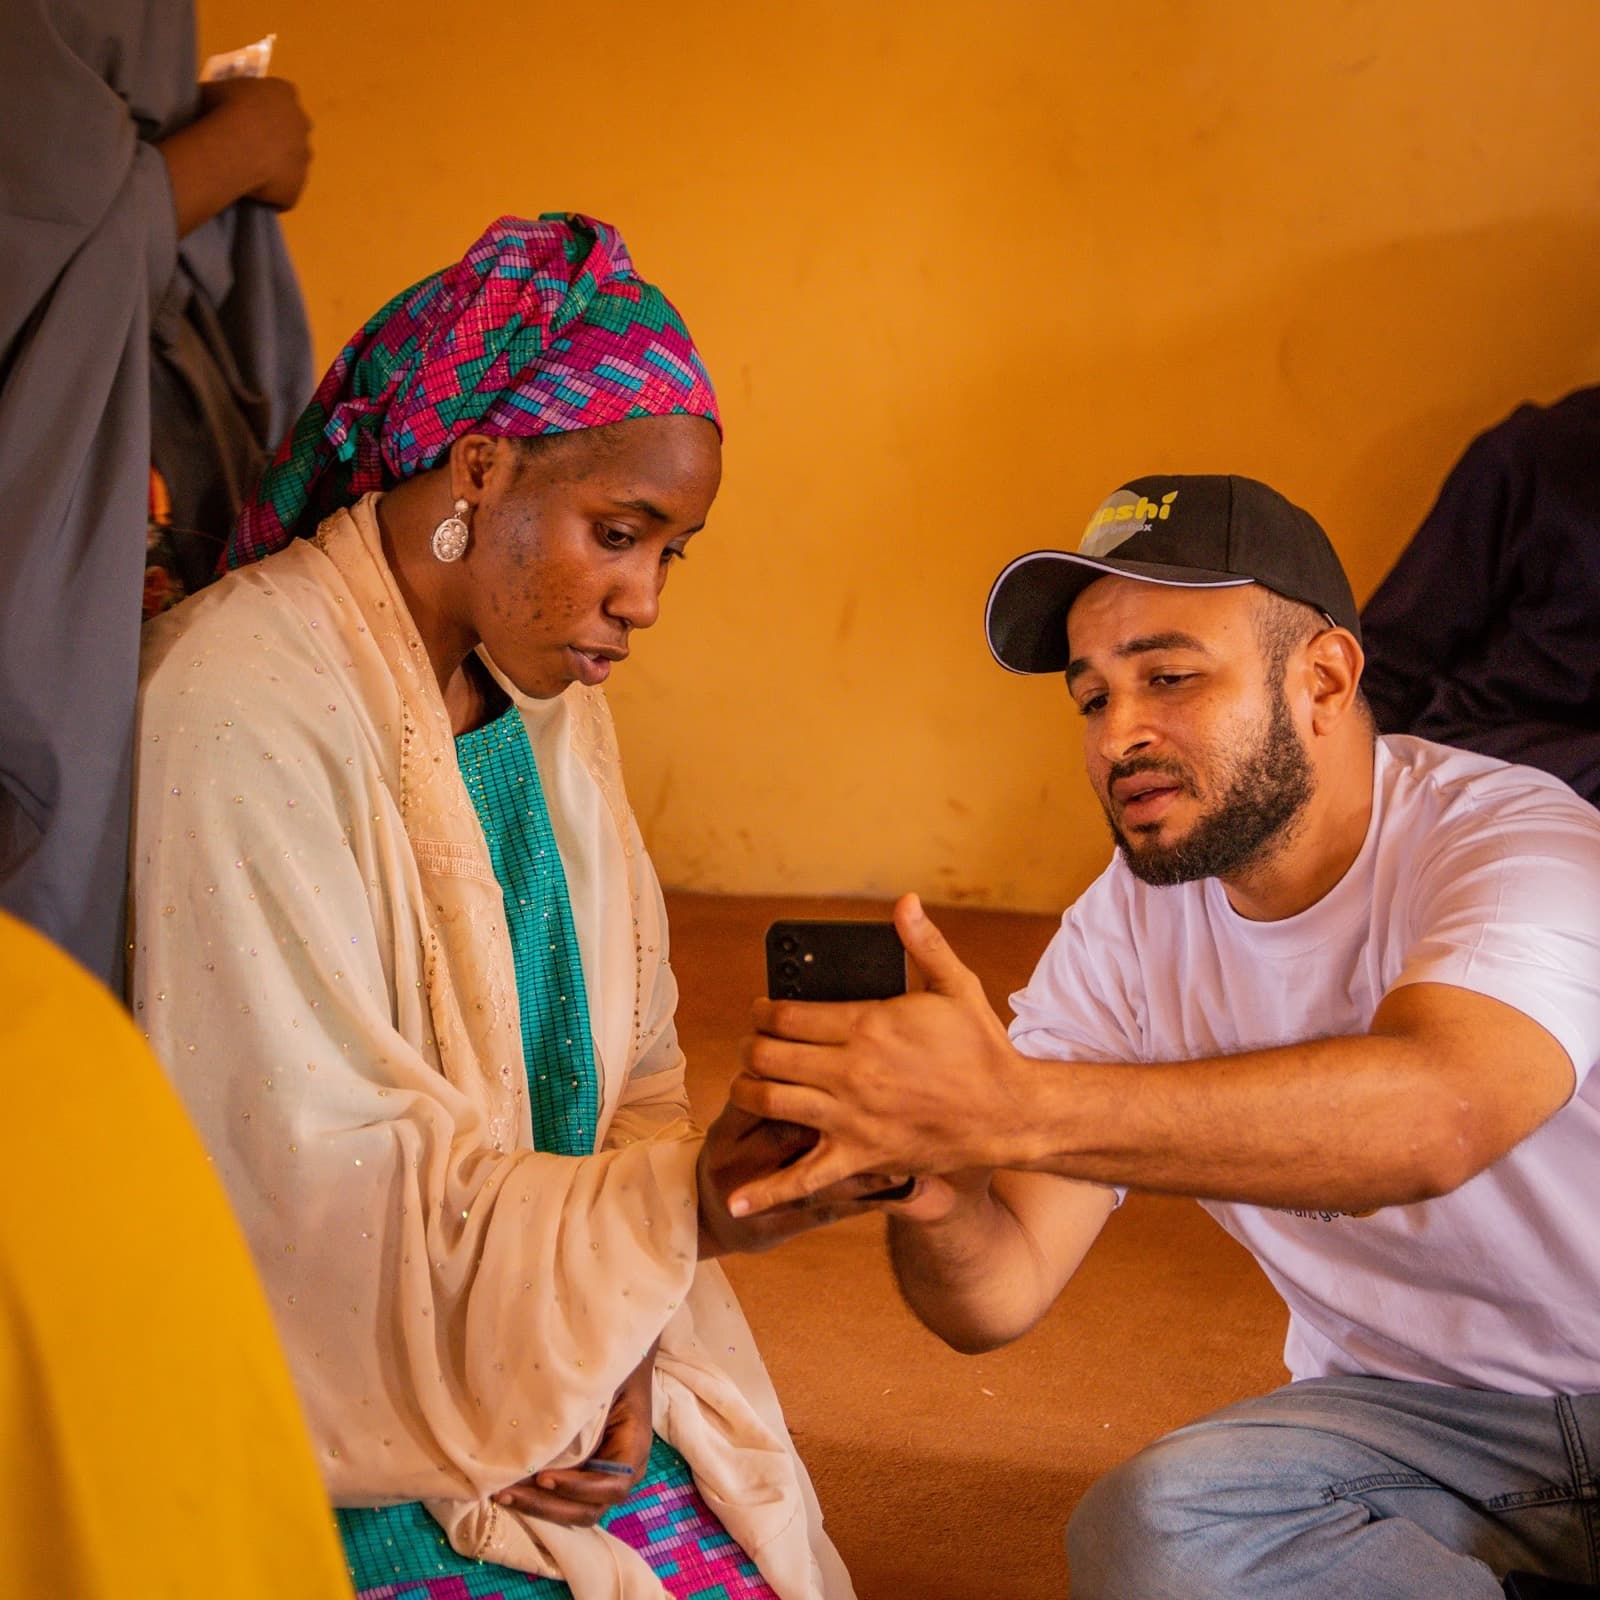
Informal women traders
Women running food, grain, provisions, tailoring or petty-trade businesses below the threshold any commercial bank will underwrite.
Smallholder women farmers
Women producing and aggregating grain, groundnut, soya and vegetables who need input and off-season working capital.
First-time digital users
Adults who have never held an account or used a digital financial service.
Market and agri-vendors
Shops and stockists who accept digital payment from Kidashi borrowers, creating a closed, traceable loop.
Community field agents
Locally resident agents, majority women, who deliver onboarding, literacy and collections.
What is already live.
Agent-led onboarding and market-day collections on a fully regulated stack.
Licensed rail
Payrep Microfinance Bank, licensed by the CBN, provides deposit, lending and settlement. Kidashi never holds customer funds outside a regulated institution.
Wallets and accounts
Tiered, identity-linked wallets, opened at the point of onboarding by the field agent.
Channels live
USSD, agent POS and the Payrep mobile app, with an agent network operating across market clusters in the North.
Credit engine
Trade-evidence underwriting from the wider XchangeBox book: turnover, offtake and repayment behaviour instead of collateral.
Policy stack
KYC/AML, consumer protection, complaints and risk policies documented and in force, with data protection applied at capture.
Governance
Board-supervised, with internal audit and a designated compliance officer at Payrep MFB.
Lessons from the wider XchangeBox book.
Kidashi sits on the same cycle-based, evidence-underwritten approach XchangeBox uses across its trade finance platform.
Short cycles beat long tenors
Matching repayment to the trading cycle keeps arrears low without heavy enforcement.
The circle works
Group endorsement filters out borrowers no credit bureau could have screened.
Agents are the product
Adoption tracks agent density far more closely than it tracks interest rate.
Literacy comes before usage
Cohorts trained before disbursement transact more often and default less.
Rooted in Northern Nigeria.
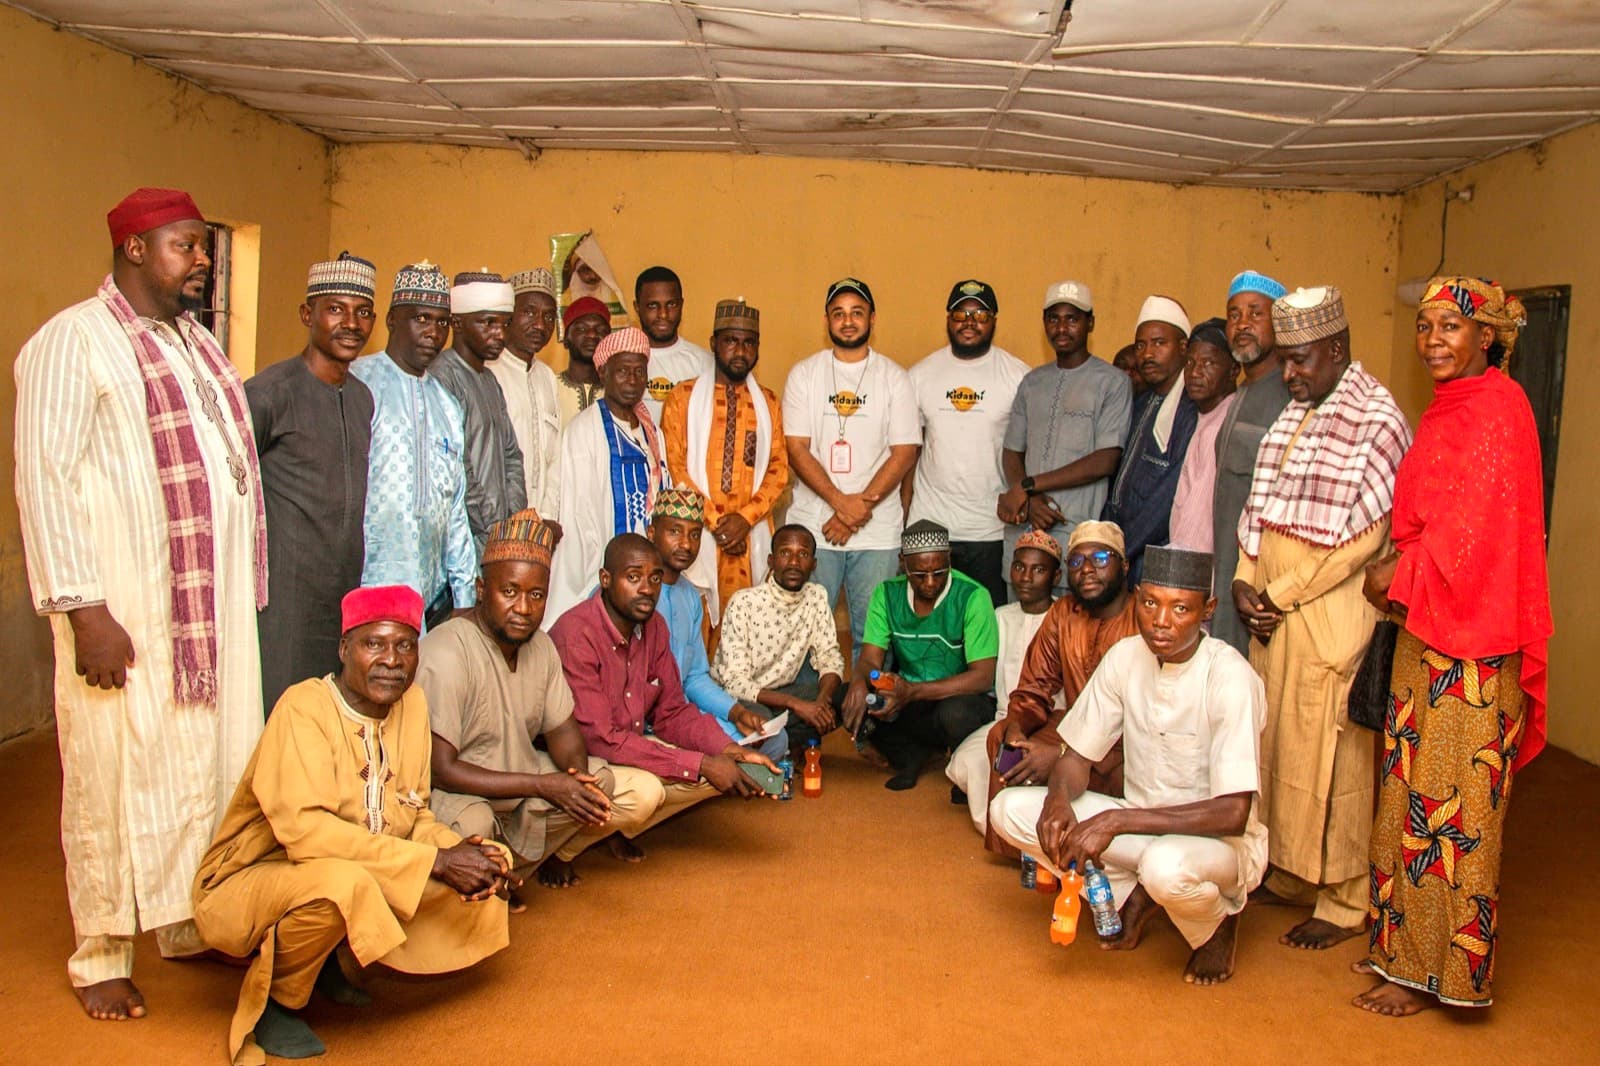
Community entry in Rigachikun, Kaduna State
Kaduna State
Anchor stateMarket clusters and agri corridors, with our agent network and literacy delivery already operating.
Kano State
Trading hubA dense trading population and the largest concentration of informal women traders in the North.
Niger State
Agrarian corridorGrain and soya aggregation, with low agent density and high financial exclusion.
Built for a basic phone, not a smartphone.
Pictorial, audio-first and vernacular, so low literacy stops being a barrier to inclusion.
Vernacular USSD
Menus in Hausa, Fulfulde, Nupe and Yoruba, so a non-English speaker can transact unaided on any handset.
Voice-prompt onboarding
Audio guidance for non-literate users through account opening, PIN setting and first transaction.
Identity integration
National identity verification wired into the Payrep core, so identity is confirmed at capture, not later.
Agent POS and app
Cash-in, cash-out, repayment collection and balance enquiry through the agent's terminal and the Payrep app.
Core banking and reporting
Payrep core banking holds the ledger, with dashboards reporting activity, arrears and gender split in near real time.
Data protection
Consent capture, encrypted storage and role-based access to customer identity data, in line with Nigerian data protection law.
Kidashi on the ground.
Community entry, literacy sessions and onboarding days across Barnawa and Rigachikun in Kaduna State.
Swipe or use the arrows to browse, then tap a video to watch it full size.
Photo gallery
Filter by event, and tap any photo to view it full screen.
Help us put working capital in her hands.
Partner with XchangeBox to fund, distribute or scale Kidashi across new communities.